
Introduction
Most of us picture retirement as a calm morning with tea, a newspaper and no alarm clock. Very few of us picture the math behind it. And that math looks very different depending on whether you rely on public schemes, private investments, or a mix of both.
Your uncle who worked in a government office probably gets a steady pension every month. Your friend in a private company may have nothing except an EPF balance and a few mutual fund SIPs. Both can retire well, but they take different roads to get there.
In this guide, we break down public vs private retirement planning in simple words. You will learn what each option offers, where each one falls short, and how to combine them. By the end, you will have a clear idea of what to do next, whatever your job or age.
What Does Public Retirement Planning Mean?
Public retirement planning means using schemes that are run, regulated or backed by the government. These are usually seen as safe and predictable. You do not need deep market knowledge to use them. You just need discipline and patience.
In India, the most common public retirement options are the Employees’ Provident Fund (EPF), the Public Provident Fund (PPF), the National Pension System (NPS) and government pension schemes for public sector employees. The Senior Citizens’ Savings Scheme (SCSS) also helps once you actually retire.
Employees’ Provident Fund (EPF)
If you work in a private or public company that is registered with the EPFO, a part of your salary goes into EPF every month. Your employer adds a matching amount. The interest rate is declared by the government each year and has stayed above 8% in recent years. That is a strong, low-risk return.
The best part is that it happens automatically. You do not have to remember to invest. The downside is that it is not enough on its own. A typical EPF balance may cover only a portion of what you need after 60.
Public Provident Fund (PPF)
PPF is a favourite for people who want safe, tax-friendly savings. You can invest up to ₹1.5 lakh per year, and the account runs for 15 years with the option to extend in blocks of five years. The interest rate is set by the government and reviewed every quarter. It has been around 7.1% in recent times, so check the latest rate before you start.
PPF falls under the “exempt-exempt-exempt” category. Your investment, the interest earned and the final maturity amount are all tax-free under the old regime rules. That makes it hard to beat for conservative savers.
National Pension System (NPS)
NPS is a market-linked pension scheme regulated by PFRDA. You choose how much goes into equity, corporate bonds and government securities. It is open to everyone, not just government employees. It also has low fund management costs, which helps your money grow.
NPS offers an extra tax deduction of up to ₹50,000 under Section 80CCD(1B) in the old regime. If your employer contributes to your NPS account, that contribution can also be deductible under Section 80CCD(2). At retirement, part of the corpus must be used to buy an annuity, which gives you a regular income. The exact split between lump sum and annuity has been revised over time, so confirm the current rule before you plan around it.
Government Pension Schemes
Government employees who joined before 2004 get a defined pension under the Old Pension Scheme. Those who joined later fall under NPS, and from April 2025 many can opt for the Unified Pension Scheme. It promises an assured payout linked to salary and years of service. For the people who qualify, this is a big advantage, because the income is guaranteed and often adjusted for inflation.
What Does Private Retirement Planning Mean?
Private retirement planning means building your retirement fund through products offered by financial companies, not through government-run schemes. You choose the instrument, the amount and the risk level. That freedom is powerful, but it also puts the responsibility on you.
Mutual Funds and SIPs
A Systematic Investment Plan (SIP) in equity mutual funds is one of the most popular private retirement tools. Over 15 to 25 years, equity has historically beaten inflation by a wide margin. A monthly SIP of ₹10,000 growing at an assumed 12% a year could build a corpus of around ₹1 crore in about 20 years. Returns are never guaranteed, but time in the market helps.
Equity gains also come with tax rules. Long-term capital gains above ₹1.25 lakh a year are currently taxed at 12.5%. Tax rules change, so always check before you decide.
Private Pension Plans and Annuities
Insurance companies offer pension plans that either build a corpus or give you a guaranteed income after a set age. Some are traditional plans, while others are unit-linked. They can give peace of mind, but many carry higher charges and lower returns than direct market options. Read the fine print about premiums, charges and payout terms before buying.
Real Estate, Gold and Other Assets
Many Indians also count property and gold as retirement assets. A second house can give rent. Gold can protect against inflation. But both are harder to sell in small pieces, and property comes with maintenance and legal trouble. Treat them as a supporting part of your plan, not the whole thing.
Other Private Options
Some people use corporate bonds, REITs, index funds or even a small business to create future income. These can work well, but they need research and a higher comfort level with risk.
Public vs Private Retirement Planning: A Side-by-Side Look
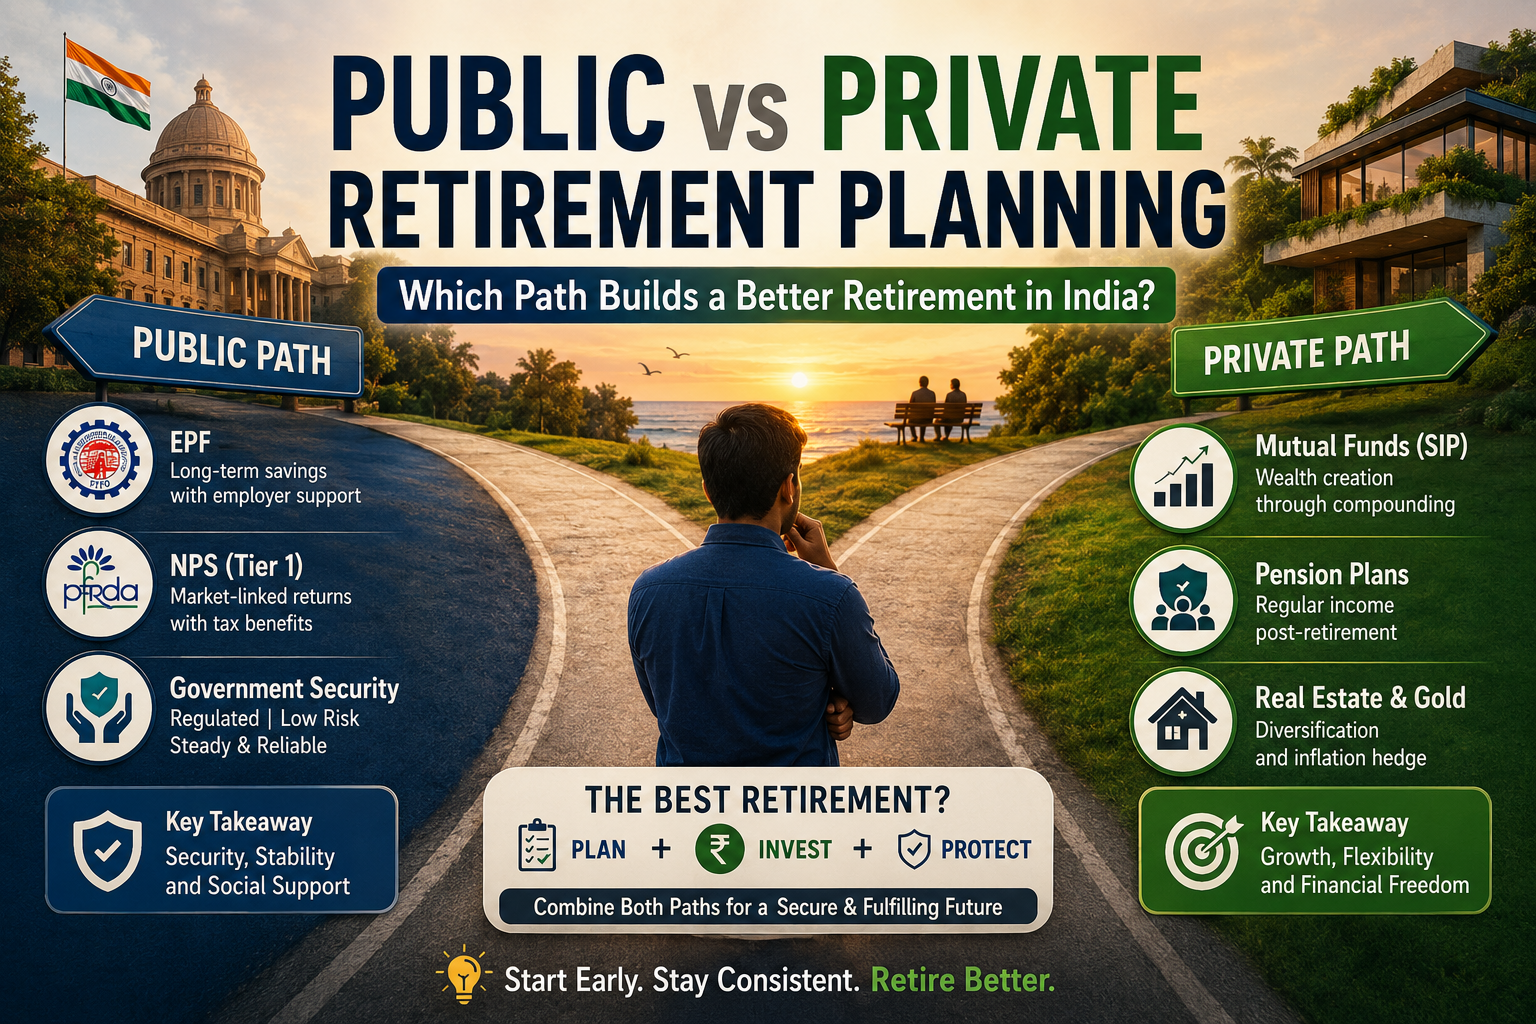
Here is the simple way to think about it. Public options give you safety and structure. Private options give you growth and flexibility.
Safety. Public schemes like PPF and EPF are backed by the government, so the risk of losing your capital is very low. Private market investments can fall in value, sometimes sharply, in the short term.
Returns. Public schemes usually earn between 7% and 8.25%. Private equity based investments can earn more over the long run, but with ups and downs. Over 20 years, even a small gap in returns becomes a big gap in the final corpus.
Flexibility. Mutual funds let you start, stop, increase or withdraw with few restrictions. PPF locks your money for years. NPS limits withdrawals until you are older.
Tax benefits. Public schemes often have clear tax advantages. Private options have tax rules too, but they vary by product and change more often.
Inflation protection. This is where many public schemes struggle. A fixed 7% return may barely beat inflation after tax. Equity based private investments have a better chance of growing your money in real terms.
Discipline. Public schemes often force you to save. Private investing needs you to stay consistent on your own.
Real-Life Examples
Ramesh, a Government Teacher
Ramesh is 35 and works as a government school teacher. He expects a pension linked to his salary and has a GPF-style provident fund as well. His base income after retirement is fairly secure. So he adds a modest SIP of ₹5,000 a month to beat inflation and fund travel and healthcare costs. His plan leans public with a small private top up.
Priya, a Private Sector Software Professional
Priya is 30 and works at a private IT company. She has no pension, only EPF. She knows EPF alone will fall short. So she opens a PPF account for stable savings, invests in NPS for the extra tax benefit, and runs an SIP of ₹15,000 a month in a mix of index and flexi cap funds. Her plan leans private with public schemes as a safety net.
Anil, a Small Business Owner
Anil runs a shop and has no employer to contribute for him. His income is uneven, so he picks flexible options. He sets up a small monthly SIP, adds to PPF when business is good, and keeps a separate emergency fund. He avoids any plan that forces a fixed monthly payment he might miss.
How to Choose the Right Mix for You
There is no single best answer to public vs private retirement planning. The right balance depends on your age, income, risk comfort and job type. These simple steps can guide you.
Step 1: Know Your Retirement Number
Estimate your monthly expenses today. Adjust for inflation until your retirement age. A person spending ₹50,000 a month today may need over ₹1.5 lakh a month in 25 years at 5% to 6% inflation. Multiply your yearly need by about 25 to get a rough target corpus.
Step 2: Cover the Basics First
Before investing for retirement, keep an emergency fund of 6 months of expenses and get proper health and term life insurance. A medical emergency can wipe out years of retirement savings.
Step 3: Use Public Schemes as Your Base
Let EPF run. Use PPF for your safe portion. Open an NPS account if you want extra tax savings and low cost investing. This gives you a stable foundation that does not depend on market moods.
Step 4: Add Private Investments for Growth
Start an SIP in diversified equity funds. The younger you are, the more equity you can usually handle. Increase your SIP amount every year when your salary grows. Even a 10% yearly step up makes a big difference.
Step 5: Shift Gradually as You Age
In your 30s, you might hold 60% to 70% in equity. By your late 50s, move more money to safer options so a market fall does not hurt right before you retire. Review your plan once a year.
Common Mistakes to Avoid
Starting too late. Waiting until 40 to begin means you must save much more each month. Starting at 25 with a small amount often beats starting at 40 with a large one.
Depending on one option. Putting everything into only PPF or only equity creates risk, either of low growth or of big losses.
Withdrawing early. Taking out your EPF when you switch jobs can break the compounding. Transfer it instead.
Ignoring inflation. A plan that looks fine today may fall short in 25 years if you do not adjust for rising costs.
Buying products you do not understand. If an agent promises “guaranteed high returns,” pause and ask for the full details in writing.
Practical Tips You Can Use Today
Set up an auto debit for your SIP on the day your salary arrives. Check your EPF passbook once a month to make sure contributions are going in. Download your NPS statement and review your asset allocation. Increase your savings rate by 1% every few months until you reach at least 15% to 20% of your income. Talk to a SEBI registered investment adviser if you feel stuck, and keep your nominee details updated on every account.
Conclusion
Public vs private retirement planning is not a fight where one side must win. Public schemes bring safety, tax benefits and discipline. Private investments bring growth, flexibility and a better shot at beating inflation. The strongest retirement plans use both.
Start with a safe base of EPF, PPF and NPS. Add equity SIPs for long term growth. Review your plan every year and adjust as your life changes. The best time to begin was years ago, and the second best time is today.
So pick one step from this guide and do it this week. Open that PPF account, start that SIP, or calculate your retirement number. Your future self will thank you.
Disclaimer: This article is for general information only and is not financial advice. Interest rates and tax rules change often, so confirm the latest details or speak with a qualified adviser before investing.